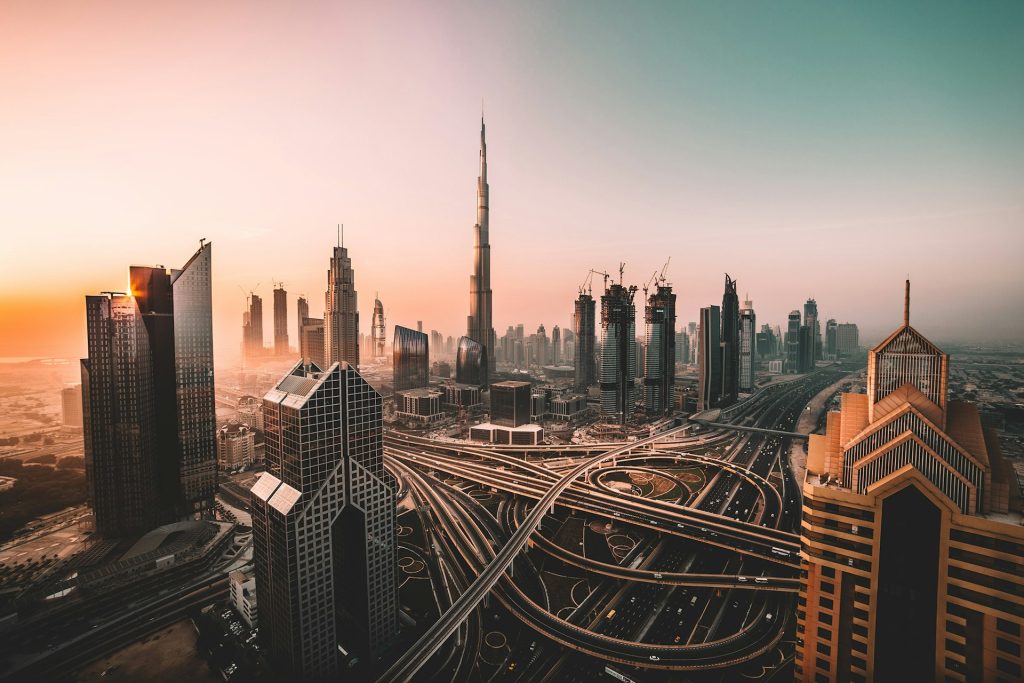
Dubai is attracting a growing number of internationally mobile entrepreneurs and wealthy families. But successful relocation involves more than obtaining residency or establishing a company. The real challenge is ensuring that personal residence, international assets, family governance and long-term succession arrangements work together.
Dubai has become an increasingly important destination for international entrepreneurs, business owners and high-net-worth families seeking a base from which to manage their personal and commercial interests.
Its appeal is compelling: an internationally connected business environment, established financial infrastructure, access to global markets and a legal framework that supports a range of wealth-holding and succession structures.
Yet one of the most common misconceptions about relocating to the UAE is that obtaining a residence visa or incorporating a company automatically delivers the intended tax and wealth-planning benefits.
In reality, the most important decisions often need to be made before relocation takes place.
For families with businesses, investments and beneficiaries across several countries, moving to Dubai should form part of a coordinated international strategy rather than be treated as an isolated change of residence.
1. UAE Residency and Tax Residency Are Not the Same Thing
Obtaining a UAE residence visa is often one of the first steps considered by internationally mobile individuals.
However, immigration residency and tax residency are distinct concepts.
UAE tax residence depends on the applicable statutory conditions, which may take into account physical presence, an individual’s usual or primary place of residence, and their personal and financial connections.
For example, UAE domestic tax-residence rules include a 183-day presence test and, subject to additional conditions, alternative tests involving 90 days or the individual’s principal residential and personal connections.
Crucially, establishing UAE tax residence does not automatically terminate tax residence in another jurisdiction.
An individual relocating from the UK, Europe or Asia may remain subject to taxation elsewhere depending on their residence history, family connections, business activities or other relevant circumstances.
The correct starting point is therefore a coordinated assessment of both the jurisdiction being left and the UAE.
2. Moving Residence Does Not Automatically Move Tax Obligations
International wealth is rarely confined to 1 country.
An entrepreneur relocating to Dubai may retain shares in an overseas trading company, hold investment portfolios through offshore entities, own property in several jurisdictions and have family members living abroad.
These connections can continue to create tax and reporting obligations even after relocation.
Recent developments concerning China’s scrutiny of offshore wealth provide a clear illustration of this wider principle.
In October 2026, the Financial Times reported on increased enforcement activity involving offshore trusts, overseas investment income and historical transactions.
The implications are relevant well beyond China: the location of a bank account, trust or holding company does not necessarily determine where the income or assets are taxable.
For internationally connected families, relocation planning must therefore consider existing tax obligations, applicable treaties, source-country taxation and the treatment of assets held through trusts or companies.
Dubai can provide an effective base for international wealth management, but it should not be viewed as a means of automatically extinguishing obligations arising elsewhere.
3. Should International Families Establish a UAE Foundation?
For families considering a long-term presence in the UAE, one of the most important questions is how their wealth should be owned, administered and transferred between generations.
The Dubai International Financial Centre (DIFC) and Abu Dhabi Global Market (ADGM) offer foundation frameworks that may be appropriate for certain family wealth structures.
A foundation can provide a legal framework through which assets are held and administered for defined purposes or beneficiaries, with governance arrangements governing management, control and succession.
Depending on the family’s objectives, a foundation may help:
- Consolidate ownership of family investments and business interests.
- Establish clear governance and decision-making arrangements.
- Support long-term succession and continuity.
- Separate the ownership of assets from their day-to-day administration.
- Provide a framework for managing wealth across generations.
The choice between a foundation, trust, holding company or combination of structures depends on the family’s circumstances and the laws of the jurisdictions involved.
Importantly, these arrangements should not be established solely for perceived tax advantages.
Their value lies in creating an appropriate legal and governance framework for the family’s assets and long-term objectives.
4. Understanding the UAE Corporate Tax Treatment of Family Foundations
The introduction of UAE Corporate Tax has made the tax treatment of family wealth structures an essential part of the planning process.
Under Article 17 of the UAE Corporate Tax Law, certain qualifying family foundations may apply to be treated as fiscally transparent for UAE Corporate Tax purposes.
This means that, where the relevant conditions are satisfied and the necessary treatment is obtained, the foundation is not subject to Corporate Tax in its own right.
However, such treatment is not automatic.
Eligibility depends on the foundation’s purpose, activities, beneficiaries and compliance with the applicable legislative requirements.
The UAE Federal Tax Authority’s updated June 2026 guidance also addresses matters involving underlying entities, special purpose vehicles and family office arrangements.
Families should therefore consider the tax treatment of the entire ownership structure rather than assuming that establishing a foundation necessarily creates a tax-neutral arrangement.
Any tax consequences arising in other jurisdictions must be assessed separately.
5. Establishing a Family Office in Dubai
As international wealth becomes more complex, many families are moving beyond traditional investment management towards more coordinated family office arrangements.
A family office can provide a central point for the administration, oversight and organisation of family assets and affairs.
Depending on the family’s requirements, this may involve investment reporting, coordination with banks and external advisers, corporate administration, governance, accounting and succession planning.
Dubai offers an attractive environment for these activities, particularly for families with interests spanning Europe, Asia, Africa and the Middle East.
However, establishing an effective family office requires careful consideration of its operating model.
The structure should reflect the family’s size, the complexity of its assets, the extent of its international activities and the degree of control that family members wish to retain.
It is also important to distinguish administrative and coordination functions from regulated financial activities, which may require specific authorisations.
A family office should be designed around the family’s actual needs, rather than assuming that every family requires an extensive standalone organisation.
6. The Importance of International Succession Planning
For first-generation entrepreneurs, relocation frequently coincides with a broader reassessment of family wealth.
Questions that may once have been deferred become increasingly important:
- Who will control the family business in the future?
- How should assets be transferred to children living in different countries?
- What happens if family members disagree?
- How can continuity be maintained following the founder’s death or incapacity?
These questions become more complex where different family members are subject to different legal and tax systems.
A UAE foundation or other appropriate holding structure may provide part of the solution, but succession planning must also take account of relevant inheritance laws, beneficiary residence, asset location and existing family arrangements.
The objective is to ensure that ownership, control and succession remain aligned as circumstances change.
7. Why Planning Before Relocation Matters
Timing is one of the most important aspects of international relocation.
Transferring shares, reorganising businesses, establishing foundations or changing the ownership of investments can have materially different consequences depending on whether these steps occur before or after a change in tax residence.
In some jurisdictions, departure can give rise to exit taxes, deemed disposals or continuing tax exposure.
Similarly, transferring existing assets into a new holding structure may trigger tax, registration costs or other obligations.
An effective relocation strategy should therefore begin with a comprehensive review of existing arrangements, followed by a coordinated plan addressing residence, corporate ownership, family wealth, succession and ongoing compliance.
Not every structure needs to be changed.
In some cases, retaining existing arrangements while improving governance and administration may be more appropriate than undertaking a wholesale restructuring.
A Long-Term Strategy, Not Simply a Change of Address
Dubai offers substantial opportunities for international families seeking an efficient and well-connected environment in which to organise their wealth and business interests.
However, the benefits of relocation depend on the quality of the underlying planning.
Tax residence, corporate structures, foundations, family office arrangements and succession should be considered as interconnected elements of a single international strategy.
The goal is not simply to establish a presence in the UAE, but to create a structure that remains appropriate as family circumstances, commercial activities and tax rules evolve.
How WTA International Can Assist
WTA International assists internationally connected individuals, entrepreneurs and families with establishing and administering wealth and corporate structures involving the UAE.
Our services encompass wealth structuring, corporate and SPV administration, trust and fiduciary coordination, family office support and governance arrangements.
We work alongside appropriately qualified tax and legal advisers in the relevant jurisdictions to ensure that UAE arrangements are considered within the context of clients’ wider international interests and obligations.
Whether considering relocation, establishing a family foundation or reviewing an existing international structure, a coordinated approach from the outset can help avoid unnecessary complexity and support long-term family objectives.
Considering relocating to Dubai or establishing a UAE wealth structure?
Contact WTA International to discuss your objectives and the practical considerations involved.
This article is provided for general information only and does not constitute legal, tax, immigration or investment advice. The appropriate treatment of any structure or relocation depends on individual circumstances and the applicable laws of each relevant jurisdiction.