Switzerland is considering tighter restrictions on foreign property ownership. For investors and wealthy families across Hong Kong, Singapore, mainland China, the Middle East and other international markets, the proposals raise important questions about real estate investment, ownership structures and long-term wealth planning.
Switzerland’s Changing Real Estate Landscape
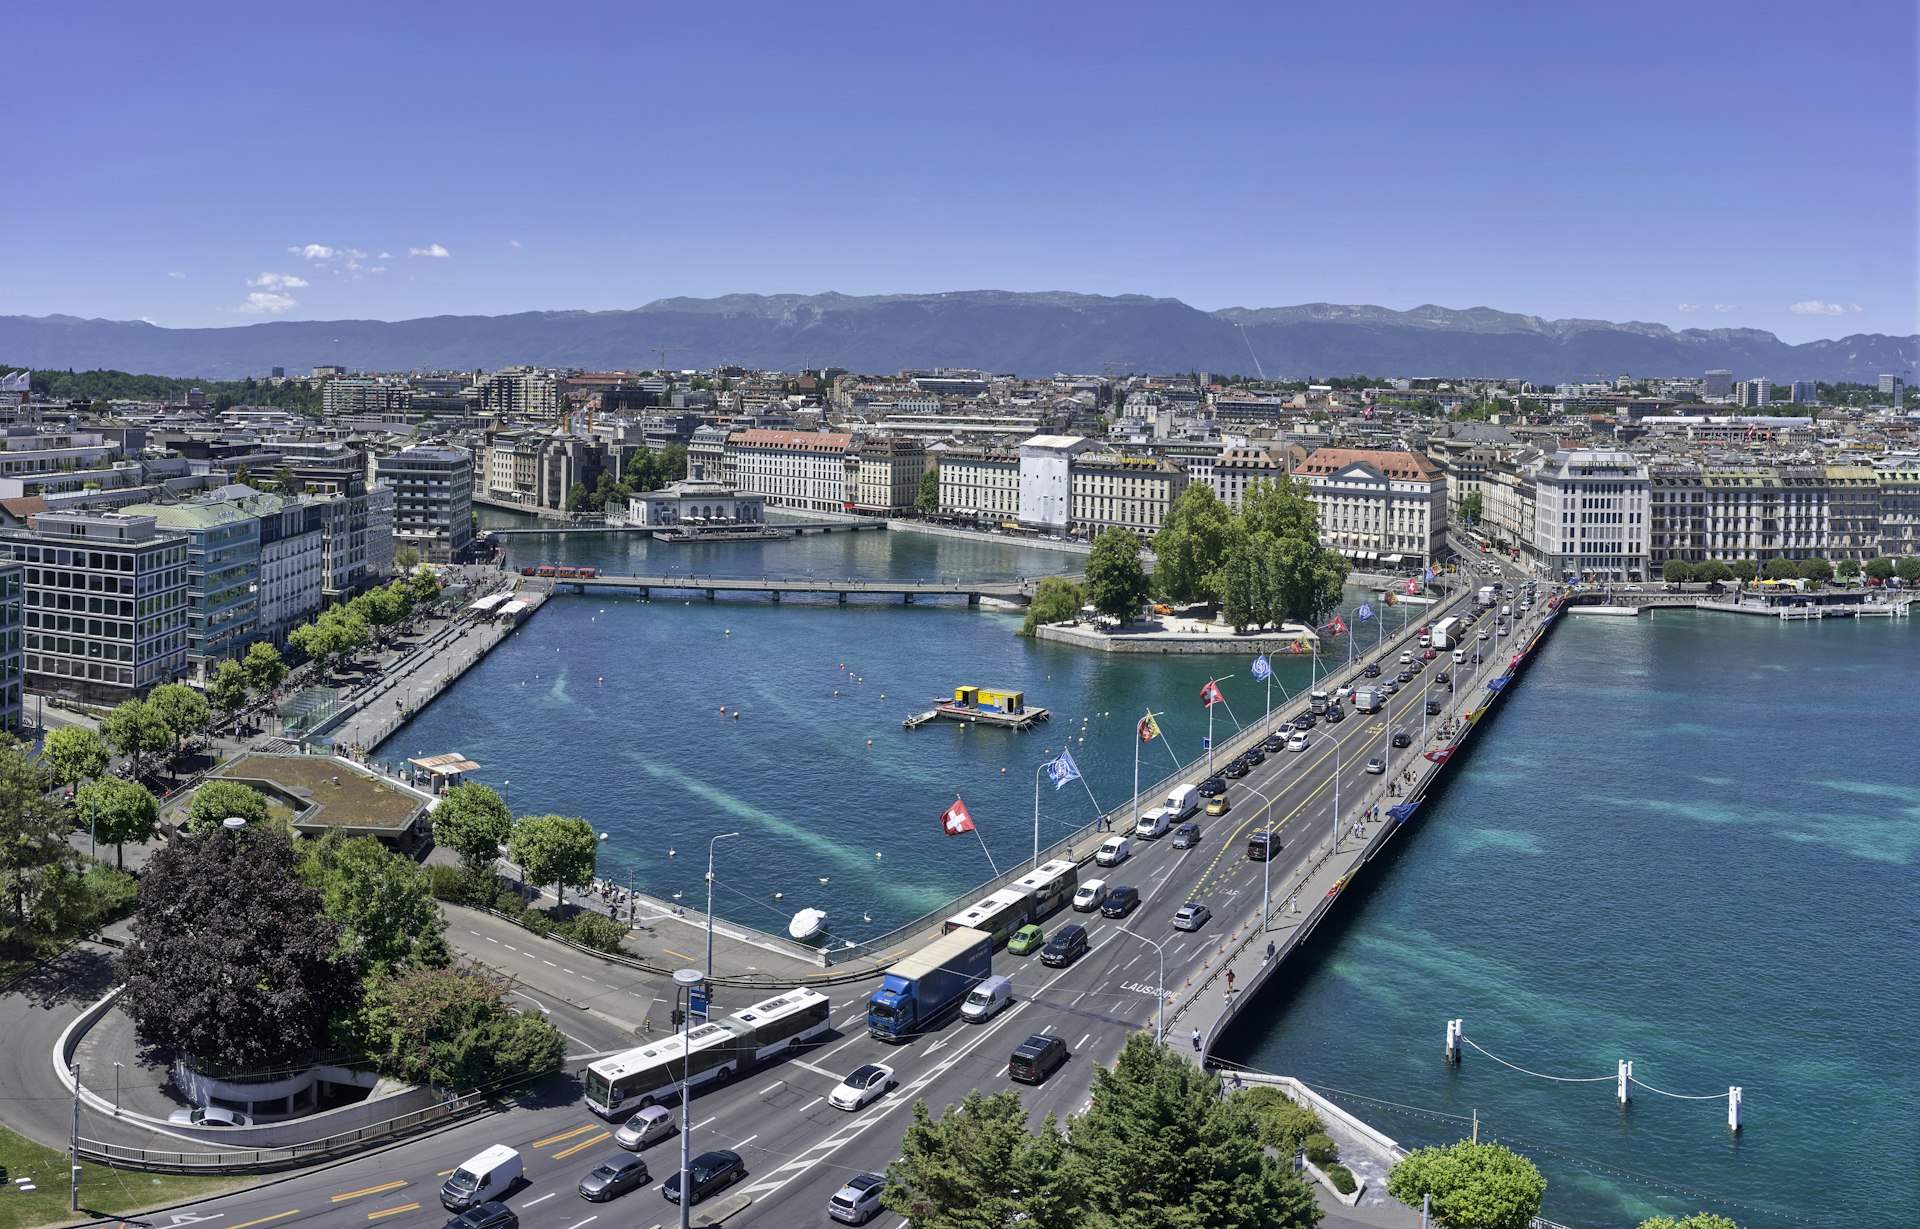
Switzerland has long been an attractive destination for international investors and high-net-worth families.
Its political and economic stability, established financial sector, strong legal framework and highly desirable residential locations have made Swiss real estate an important component of many international wealth portfolios.
From Geneva and Zurich to Gstaad, Verbier and St. Moritz, Swiss property continues to attract interest from investors seeking geographical diversification, long-term asset ownership and opportunities to establish a European presence.
However, Switzerland is considering significant changes to the legislation governing property acquisitions by foreign nationals and foreign-controlled entities.
On 15 April 2026, the Swiss Federal Council launched a consultation on proposed amendments to the Federal Act on the Acquisition of Immovable Property by Persons Abroad, commonly known as Lex Koller.
The proposed reforms could affect several categories of property acquisitions, including residential homes, holiday properties, commercial real estate investments and certain indirect interests in Swiss property.
For internationally connected investors, particularly those based in Asia and the Middle East, these developments warrant careful consideration.
While the consultation closed on 15 July 2026, the proposed amendments have not automatically entered into force and remain subject to the Swiss legislative process.
Understanding Lex Koller: Why Foreign Ownership Matters
Unlike many international real estate markets, Switzerland imposes restrictions on the acquisition of certain properties by persons abroad.
Under the existing Lex Koller framework, an investor’s ability to acquire property may depend on several factors:
- Nationality and residence status.
- Whether the purchaser is an individual or legal entity.
- The property’s classification and intended use.
- The location of the property and applicable cantonal rules.
- The ownership and control of any company or other structure used for the acquisition.
Foreign investors cannot assume that purchasing through an overseas company, trust or other holding arrangement removes these restrictions.
Swiss law may examine the ultimate ownership and control of an acquiring entity, meaning that an indirect acquisition can still fall within Lex Koller.
The relevant Swiss authorities determine whether authorisation is required and whether an exemption applies.
For international families accustomed to holding assets across multiple jurisdictions, understanding these rules before making an investment commitment is essential.
What Changes Are Being Proposed?
The Federal Council’s proposed reforms are intended to tighten the existing framework in several areas.
1. Greater restrictions on principal residences
Under the current regime, certain foreign nationals legally and actually resident in Switzerland can acquire their principal residence without Lex Koller authorisation.
The proposals would introduce additional authorisation requirements for certain non-EU/EFTA nationals acquiring a principal residence.
They also contemplate restrictions affecting the continued ownership of such properties after an individual leaves Switzerland, including disposal requirements in specified circumstances.
This could have significant implications for internationally mobile families considering Switzerland as a future place of residence.
An entrepreneur based in Hong Kong, Singapore or Dubai who plans to relocate to Switzerland may therefore need to assess not only their initial eligibility to purchase, but also what happens if the family subsequently relocates elsewhere.
2. Tighter controls over holiday homes
Swiss holiday properties remain attractive to international families, particularly in established Alpine destinations.
However, foreign acquisitions are already subject to restrictions, including authorisation requirements, location-specific conditions and cantonal quotas.
The proposed amendments would tighten aspects of these arrangements, potentially affecting both acquisitions and subsequent transfers.
For families purchasing a Swiss holiday property as a long-term asset intended to be passed to future generations, the implications extend beyond the original transaction.
Future ownership transfers, changes in residence and succession arrangements may all require consideration.
3. Increased scrutiny of commercial property acquisitions
The proposals also address the treatment of commercial real estate.
Under existing rules, qualifying commercial property acquisitions generally benefit from exemptions from Lex Koller authorisation.
The proposed reforms would narrow certain exemptions, drawing a stronger distinction between premises acquired for genuine business operations and commercial property acquired primarily as a financial investment.
This may be particularly relevant to international investors acquiring Swiss commercial property for rental income or through investment-holding structures.
For investment groups and family offices, the precise nature and purpose of a transaction may therefore become increasingly important.
4. Restrictions on indirect real estate investments
The proposed revisions would also affect certain indirect investments in Swiss residential real estate.
These include specified interests in publicly traded property companies, real estate funds and investment companies.
For investors seeking Swiss property exposure through financial instruments rather than direct ownership, the proposals highlight the importance of understanding how the underlying assets and investment vehicles are classified.
Not every investment in a Swiss real estate-related business is necessarily treated in the same way.
Why Investors in Hong Kong, Singapore and Asia Should Pay Attention
Switzerland has historically played an important role in the international wealth strategies of Asian entrepreneurs and families.
For investors based in Hong Kong, Singapore, mainland China and other Asian financial centres, Swiss assets can provide geographical diversification and exposure to European markets.
However, property ownership differs from holding securities, bank deposits or other financial investments.
It involves local acquisition restrictions, property-related taxation, legal title, financing considerations and potentially complex succession arrangements.
The proposed Lex Koller reforms reinforce several important considerations.
First, residence in an international financial centre does not necessarily determine eligibility to acquire Swiss property.
An investor’s nationality, actual residence and legal status under Swiss law can be more significant than the location of their bank accounts or family office.
Second, the use of international holding structures does not automatically improve acquisition eligibility.
A company incorporated in Singapore, Hong Kong or the UAE may still be treated as foreign-controlled for Swiss property acquisition purposes.
Third, the long-term ownership strategy matters as much as the initial purchase.
A property acquired as a family residence, holiday home or investment may subsequently be transferred, inherited or reorganised.
Each event can raise separate legal and tax questions.
For Asian families with members residing in multiple countries, these considerations are particularly relevant.
The Importance of Cross-Border Ownership Structuring
International families often own assets through a combination of personal holdings, companies, trusts and other legal arrangements.
These structures may have been developed over many years to manage investments, provide governance and facilitate succession.
When Swiss property is introduced into an existing international portfolio, the choice of ownership structure must be carefully assessed.
The appropriate arrangement may depend on:
- Whether Swiss law permits the proposed purchaser to acquire the property.
- The intended residential, commercial or investment use.
- The tax residence of the owner and relevant family members.
- The interaction between Swiss law and the family’s existing structures.
- Financing arrangements and ongoing administration.
- Future transfers, inheritance and succession objectives.
There is no universally appropriate structure.
Direct personal ownership may be suitable in some circumstances, while other arrangements may warrant consideration where legally permitted and commercially justified.
The objective should be to establish ownership arrangements that are legally compliant, administratively practical and consistent with the family’s wider international strategy.
Taxation and Succession: Looking Beyond the Acquisition
Swiss property investment should not be considered solely from the perspective of acquisition eligibility.
Depending on the asset and the investor’s circumstances, ownership may give rise to Swiss taxes and obligations, including property-related taxes, taxation of rental income, wealth taxes, capital gains taxes or inheritance and gift taxes.
The rules can differ between cantons.
Investors may also face additional tax consequences in their country of residence or through existing international ownership structures.
For example, a family residing in Singapore may have different tax considerations from a family resident in the UK or mainland China.
Likewise, a family with beneficiaries spread across several jurisdictions may encounter different inheritance, succession and reporting requirements.
Tax treaties, domestic legislation and the classification of relevant structures can all influence the outcome.
The proposed Lex Koller revisions make it particularly important to ensure that tax and succession arrangements are considered together with the legal ability to acquire, retain and transfer Swiss property.
What About Existing Swiss Property Owners?
The proposed reforms are relevant not only to prospective investors but also to families already holding Swiss real estate.
Existing owners should consider whether planned changes in personal circumstances or ownership structures could create new regulatory consequences.
These may include:
- Relocating to or from Switzerland.
- Transferring property between family members.
- Reorganising an existing holding company.
- Changing ownership or control of an entity that holds Swiss property.
- Implementing inheritance or succession arrangements.
- Disposing of an asset or transferring it to another foreign purchaser.
The ultimate impact will depend on the final legislation, applicable transitional provisions and the circumstances of each ownership arrangement.
The proposals should not be interpreted as requiring all existing foreign owners to sell their properties.
Nevertheless, investors contemplating transactions or restructurings should assess the potential consequences before taking action.
Why International Investors Should Review Their Plans Now
Regulatory change can affect property investment decisions well before new legislation enters into force.
For prospective purchasers, uncertainty regarding future authorisation requirements may influence transaction structuring, timing and long-term planning.
For existing owners, the proposed reforms provide an opportunity to review whether current arrangements remain appropriate.
A structured review should consider the investor’s objectives, existing assets, relevant jurisdictions and the potential consequences of future changes.
In particular, investors should establish:
- Whether the proposed or existing acquisition complies with Swiss law.
- Whether any authorisation or exemption is required.
- Whether the existing ownership structure remains appropriate.
- How residence changes or future transfers could affect the investment.
- Whether tax, governance and succession arrangements remain aligned.
Where a transaction involves Swiss legal requirements, advice should be obtained from appropriately qualified Swiss specialists before implementation.
International Wealth Planning Requires a Coordinated Approach
For sophisticated investors, Swiss property often forms part of a considerably broader international financial and family landscape.
An entrepreneur based in Hong Kong may operate businesses throughout Asia, maintain investment portfolios in Singapore, own property in Switzerland and have children studying or living in Europe.
The legal and tax implications of these arrangements cannot be assessed independently.
An effective wealth strategy should connect asset ownership, tax residence, corporate structures, family governance and succession planning across the relevant jurisdictions.
The proposed Lex Koller reforms illustrate why international asset ownership requires continuing oversight rather than a one-time structuring exercise.
As laws evolve and family circumstances change, structures should be reviewed to ensure they remain appropriate for their original purposes.
How WTA International Can Assist
WTA International is a UAE-based advisory boutique serving internationally connected entrepreneurs, high-net-worth families, investors and family offices across Asia, the Middle East and other global markets.
We assist clients with international wealth and corporate structuring, trust and fiduciary coordination, family office support, governance and the administration of cross-border arrangements.
For clients considering Swiss property investments, we can assist in evaluating how an acquisition or existing property holding fits within their broader international wealth strategy.
Working alongside appropriately qualified Swiss legal and tax specialists, we help coordinate the relevant ownership, structuring, administrative and succession considerations.
Our approach focuses on developing coherent international arrangements that reflect clients’ commercial interests, family circumstances and long-term objectives.
International wealth planning is not simply about deciding where to invest. It is about understanding how assets can be owned, governed and transferred across jurisdictions and generations.
Considering Swiss property as part of your international investment or family wealth strategy? Contact WTA International to discuss the wider structuring and governance considerations.
This article reflects the Swiss Federal Council’s proposed Lex Koller reforms announced on 15 April 2026. The consultation closed on 15 July 2026, and the proposed amendments remain subject to the legislative process. This article is provided for general information only and does not constitute Swiss legal, tax, immigration or investment advice.